Corporate debt restructuring in São Paulo, Brazil
Renegotiation, enforcement defence and reorganisation must be compared against the liabilities and the viability of the business. We assess these factors to choose a timely strategy, without assuming one route is always better or cheaper.
5,0 · 18 Google reviewsJudicial reorganisation is not automatic, nor does it require exhausting every negotiation first. Direct renegotiation, enforcement defence and out-of-court reorganisation should be compared against urgency and viability. An out-of-court plan may bind only participating creditors (art. 162); extending it to covered non-signatories requires more than half of the claim value in each covered category under art. 163. A liabilities map guides the choice.
Where we can act.
- Bank and supplier debtStructured renegotiation, extended terms and settlements backed by security, before it becomes enforcement.
- Enforcement already filedDefence, challenges, disputes over abusive charges and substitution of attachments that paralyse the business.
- Attachment and frozen accountsUrgent action against seizures that lock the cash and stop the company trading.
- Partners pursued personallyDefence in the veil-piercing incident and a clear line between company debt and partner debt.
- Out-of-court reorganisationA plan negotiated outside the courts and taken for approval, with the quorum the statute requires.
- Judicial reorganisationWhere it is the route, we handle the petition, the plan and the relationship with creditors and the administrator.
- Simplified regime for small businessThe special plan under Law 11,101/2005 for micro and small companies, with no creditors’ meeting.
Three legal points that guide the strategy.
The first is breathing room. Once reorganisation proceedings are admitted, enforcement of claims subject to the process is generally stayed for 180 days, extendable once for an equal period, exceptionally and provided the company did not cause the delay (art. 6, §4). The period starts on admission, not when the plan is ready. Tax enforcement and excluded claims follow separate rules; creditor-proposed alternative plans also have specific rules under art. 6, § 4-A.
The second is who is not in the pot. Art. 49, §3 excludes from reorganisation claims secured by fiduciary lien, finance leases, irrevocable promises to sell real estate and retention of title. But there is a meaningful protection: during the stay, those creditors cannot remove from the premises capital goods essential to the business. Knowing which debts fall outside changes the viability calculation entirely.
The third is who may apply. Art. 48 requires regular activity for more than two years plus four further conditions, among them not having obtained judicial reorganisation in the past five years. A company that fails the requirements needs another strategy — and finding that out through a rejected petition is the worst possible outcome.
How we run the case.
- Mapping the liabilitiesEvery debt with amount, creditor, security, stage and deadline. Without that map, any decision is a guess.
- Separating what is negotiableClaims inside and outside the process, essential assets, secured creditors. That defines the room to manoeuvre.
- Direct negotiation where appropriateWe assess extensions, discounts and security that creditors may accept, without promising agreement or delaying necessary court action.
- Defence in what is already in courtChallenges, review of charges, substitution of attachments and assessment of limits on attachment of business revenue.
- Out of court or in courtWe compare out-of-court approval and a judicial petition against urgency, eligibility and viability, without requiring prior failed negotiations.
What to bring to the first conversation.
Documents that speed up the review
To tell you whether a route outside judicial reorganisation remains, we need to see the size and the shape of the liabilities. Bring whatever exists.
- Schedule of debts by creditor and amount
- Bank and financing agreements
- Financial statements for the last three years
- Bank statements and recent cash flow
- Service of process in pending enforcement
- Protest certificates and credit bureau listings
- Articles of association and latest amendment
- Schedule of company assets and security given
First diagnosis and a written proposal before any step is taken. Informational content under Brazilian Bar Association Rule 205/2021 — it does not replace an assessment of your case.
What clients say on Google.
“From the very start I was looked after exceptionally. The team is attentive and explains every step.”
Amanda M. · Google“Excellent, highly qualified professionals. I highlight the professionalism, the service and the honesty.”
Rita G. · Google“Very polite, patient, always with precise, accurate answers. I recommend them with no reservations!”
Thais T. · GoogleReal client reviews published on Google.
Who leads this area.
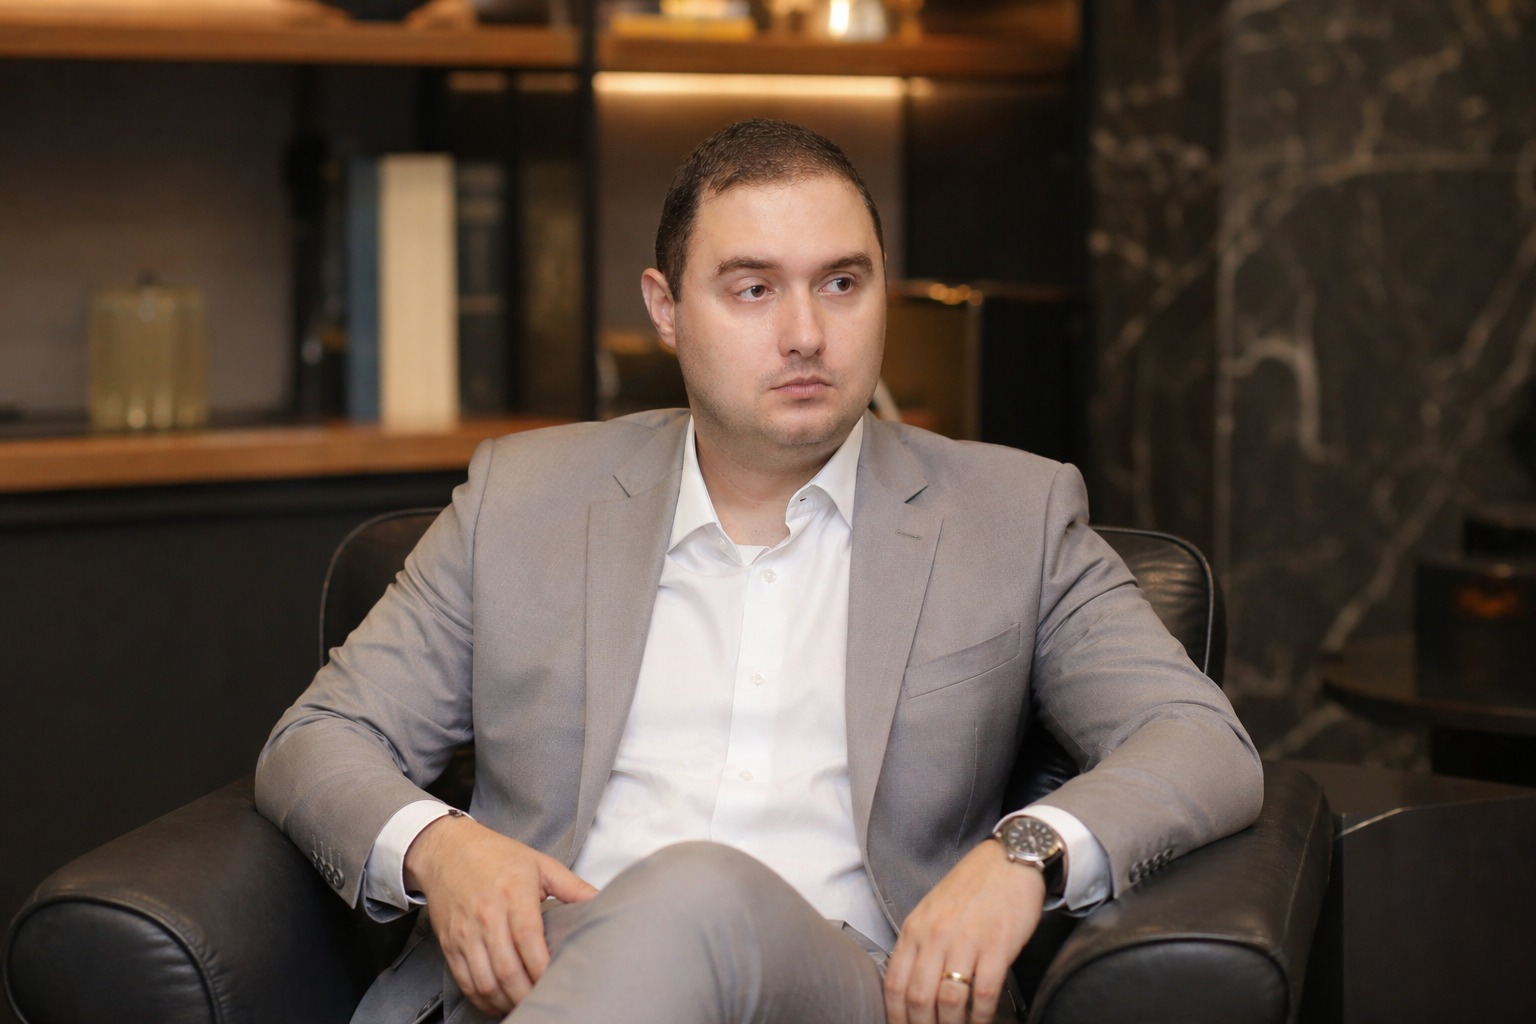
Partner in charge of the corporate practice (OAB/SP 344.334). Postgraduate in Business Law (FGV), acting in debt restructuring, contracts, corporate matters and credit recovery. Member of AASP and of the AIPLA. Fluent in English.
Meet Renato FalchetCommon questions.
Our company is in debt. What comes first?
Mapping the liabilities before any decision: every debt with amount, creditor, security and procedural stage. That is what shows whether the problem is cash, capital structure or operations — and each diagnosis leads somewhere different. Companies that negotiate without the map tend to settle badly with the loudest creditor rather than the most important one.
Is judicial reorganisation always the answer?
No. Judicial reorganisation involves costs, publicity and eligibility conditions, including more than two years of regular activity and the restrictions in art. 48 of Law 11,101/2005, including earlier reorganisations within the statutory period. Renegotiation, enforcement defence and out-of-court reorganisation may be alternatives, but need not be exhausted before a necessary and viable court petition.
What is out-of-court reorganisation and when does it pay?
It is a negotiated plan submitted for court approval, with publicity and an opportunity for creditors to object. Under art. 162 it binds participating creditors. To bind all covered creditors, art. 163 requires more than half of the claim value in each included category; the petition may start with at least one third of each category and a commitment to reach the threshold within a non-extendable 90 days from filing. Not every claim is eligible, and suitability depends on the liabilities.
Are the partners’ personal assets at risk?
The company and its shareholders have separate assets. Under the general civil rule in Civil Code art. 50, veil piercing requires abuse through misuse of purpose or commingling, with a right to respond; it may be sought in the initial claim or through a separate procedural application. Personal guarantees, negotiable-instrument guarantees and statutory liabilities, including labour or tax liabilities, require specific analysis and do not always depend on that same procedure.
Can the bank take the machinery the company produces with?
Claims secured by fiduciary lien and finance leases are not subject to judicial reorganisation (art. 49, §3). But the same provision prevents those creditors, during the stay, from removing from the premises capital goods essential to the business. This protection does not extinguish the debt or automatically cover cash or receivables: the asset’s nature, possession and essential use must be established.
Is there a simpler regime for small companies?
Yes. Law 11,101/2005 provides a special plan for micro and small companies, with payment in up to 36 monthly instalments bearing interest equivalent to the Selic rate, the first falling due within 180 days of the petition, and no creditors’ meeting. It does not cover every claim, and the intention must be stated in the initial petition.
What does it cost, and do you act outside São Paulo?
The diagnosis comes first. From there, fees are agreed in writing: a fixed fee for renegotiation and discrete defence work, a monthly retainer for ongoing support, and a specific proposal for out-of-court or judicial reorganisation. We act for companies across Brazil, instructing local agents under our supervision where proceedings run elsewhere.
Is the debt still negotiable?
Send the schedule of what the company owes and to whom. We run the diagnosis and tell you which door is still open. The review timetable is confirmed after we receive the documents.